


By Tinotenda Bhunu
HARARE – FOR years, the most important price in Zimbabwe hasn’t always been the one printed on a bank screen. It’s been the price people are actually willing to pay for foreign currency.
A shopkeeper knows it. So does an importer, a manufacturer, a parent trying to pay school fees, or a small trader who needs to restock tomorrow. When the official exchange rate says one thing while the market says another, the economy isn’t just dealing with two prices. It’s dealing with two competing sets of information. And bad information is expensive.

Zimbabwe now appears to be entering a different phase of its long-running currency experiment. The Reserve Bank of Zimbabwe is preparing to introduce an electronic foreign-exchange trading system designed to improve the matching of buyers and sellers and strengthen price discovery. The IMF has called the platform an important step towards more transparent, market-based FX trading, while noting that authorities are also developing a broader strategy to liberalise the foreign-exchange market and reform the RBZ’s intervention framework. The RBZ’s own 2026 Foreign Exchange Transactions Guidelines describe a similar objective: real-time quotations, faster execution, and a daily reference rate based on the weighted average of actual willing-buyer-willing-seller interbank transactions.
This might sound like a technical banking reform. It isn’t. It goes to the heart of Zimbabwe’s monetary problem.
An exchange rate, at the end of the day, is a price. Like the price of maize, fuel, property or a bus ticket, it carries information. If foreign currency is scarce and many people want it, the price should reflect that scarcity. If it becomes more abundant, the price should reflect that too. That’s one of the basic functions a market is supposed to perform, and the trouble starts when the price is prevented from performing it.
Zimbabwe has lived through this before. The World Bank’s earlier assessment of the country’s FX system found that restrictions and distortions in the official market fed a parallel-market premium, and recommended greater flexibility and transparent, market-driven price discovery. The lesson is simple enough: if the official rate doesn’t reflect what businesses and households are actually experiencing, people don’t stop needing foreign currency. They just go find a price elsewhere. The parallel market becomes a shadow price, and the economy ends up making decisions off two different sets of information at once.
The new electronic platform could change that. Instead of leaning heavily on administrative mechanisms to decide who gets foreign currency and at what price, a functioning electronic market lets authorised dealers place orders, match buyers and sellers, and generate a price out of actual transactions. That’s the theory, anyway. The RBZ has already signalled this direction. Its 2026 Monetary Policy Statement said the platform is meant to build a more competitive, transparent, credible and flexible FX market, with more room for market forces to operate. The IMF’s latest review backs this up, describing the platform as an important step while Zimbabwe works out a fuller liberalisation strategy.
Which raises the real question. It’s no longer simply whether Zimbabwe has an exchange-rate policy. It’s whether Zimbabwe has a market capable of discovering a rate that people actually trust. Those are two different things.
This is where Zimbabwe needs to be careful, because putting FX trading on an electronic platform doesn’t automatically create a free or competitive market. A sophisticated platform can still spit out a distorted price if the underlying rules distort participation. If banks can’t freely match legitimate demand and supply, if participants run into unnecessary restrictions, if intervention is unpredictable, or if the central bank tries to suppress the price whenever it becomes politically inconvenient, then the technology just digitises the old problem. The machine can match orders. It can’t manufacture confidence, and that comes from the rules governing the market itself.
So the RBZ faces a real institutional test: can it let the market reveal information even when that information is uncomfortable? A market-based rate might sometimes move in a direction policymakers don’t like. That’s precisely why price discovery matters. A price that’s allowed to move tells policymakers something useful; a price that’s prevented from moving just hides the problem until it gets bigger.
Which is why Zimbabwe should keep an eye on one number beyond the official rate: the gap between the official market and the parallel market. If the new system works, the official rate should increasingly reflect genuine market conditions. That doesn’t mean the rate will stop moving. It means the movements should increasingly be explained by real demand and supply rather than by administrative decisions. A narrow gap achieved through genuine convergence is one thing. A narrow gap achieved through enforcement or suppression of alternative markets is something else entirely. The first is price discovery. The second is just price control dressed up differently. Zimbabwe should want the first.
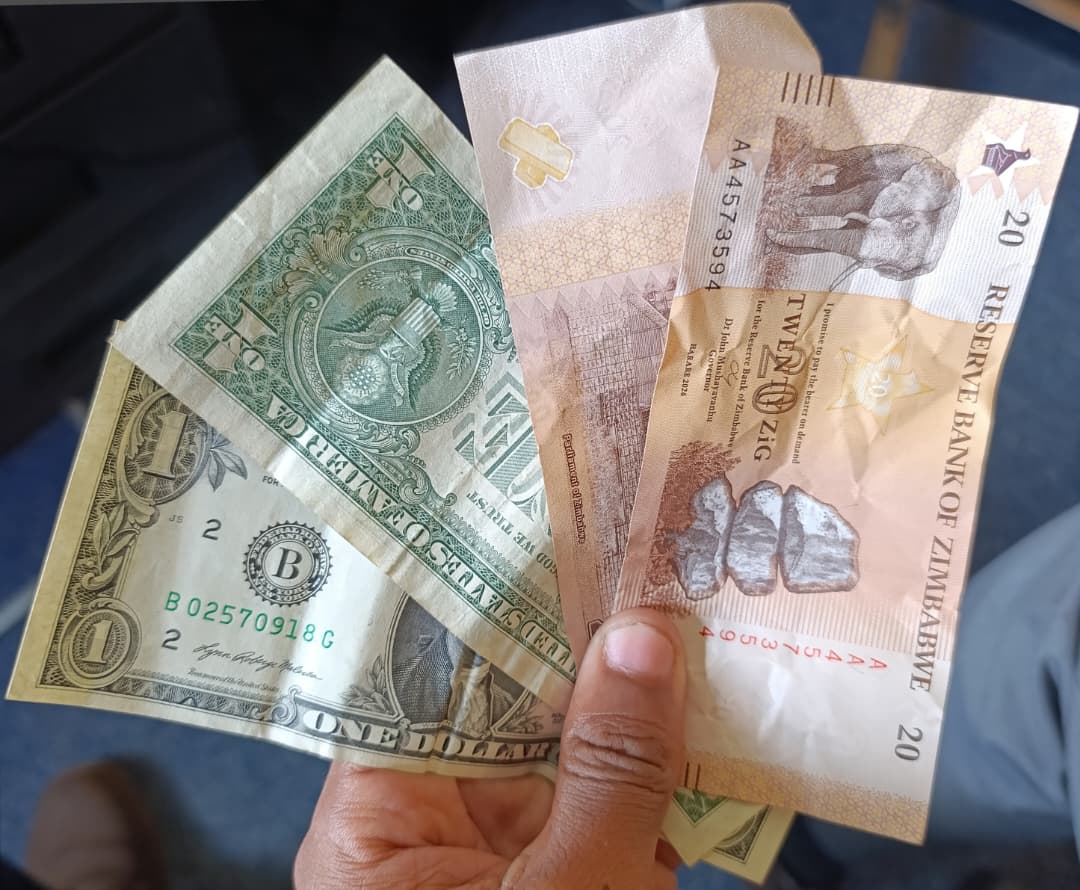
Then there’s the more politically sensitive piece of this: the proposed move towards a mono-currency. The government has again ruled out forcibly converting people’s foreign-currency balances into ZiG. Governor John Mushayavanhu and Finance Ministry Permanent Secretary George Guvamatanga have said holders of foreign-currency accounts will keep their balances, and contracts entered into in foreign currency will continue to be honoured in that currency, while local transactions under a future mono-currency arrangement would be settled in the domestic currency.
That distinction matters. A mono-currency system doesn’t have to mean confiscating people’s foreign currency, but it does mean the domestic currency needs to become genuinely useful and credible enough that people choose to use it. That can’t be legislated into existence. It has to be earned, and to their credit, the authorities seem to recognise this. The transition has increasingly been framed as conditional on macroeconomic stability rather than tied to a fixed date on a calendar.
There’s been some real progress. The World Bank credits fiscal and monetary discipline with bringing local-currency inflation into single digits in early 2026, alongside average real GDP growth of nearly 6 percent between 2021 and 2025, though the Bank is careful to add that this growth hasn’t yet translated into broad gains in jobs or household incomes. The RBZ’s latest figures put year-on-year ZiG inflation at 2.89 percent as of August 2026. These are meaningful improvements, but price stability is only one piece of monetary credibility. People also need to believe the exchange rate is genuinely discoverable, that foreign currency is accessible through legitimate channels, and that today’s rules won’t be rewritten tomorrow.
That’s where institutions come in. Zimbabwe has a long memory when it comes to money. People remember bank balances losing value, exchange-rate gaps, queues, changing rules, and being told one rate was correct while businesses priced goods using another. That history matters, because money is ultimately built on trust. A currency isn’t valuable just because a central bank gives it a name; people hold it because they believe someone else will accept it tomorrow. That’s why the government’s latest reassurance on foreign-currency accounts isn’t just PR. It’s part of rebuilding confidence in the financial system. But the bigger challenge is building confidence in the local currency itself. The goal shouldn’t be getting Zimbabweans to use the ZiG because they have no alternative. It should be creating conditions under which they choose to use it. There’s a world of difference between the two.
Zimbabwe’s economic policy debate has often focused on what the exchange rate should be. The more useful question is who should determine it. If the answer is the market, the policy architecture has to actually be consistent with that answer: legitimate buyers and sellers participating freely, transparent rules, reliable transaction-based data, minimal discretionary allocation of foreign currency, a rate that’s allowed to respond to real supply and demand, and central-bank intervention that’s predictable and limited rather than a backdoor way of setting the price. And it means fiscal discipline, because no FX platform can permanently make up for a government that spends beyond its means and expects monetary policy to clean up afterward. The World Bank makes this connection explicitly: prudent fiscal policy helps anchor price and exchange-rate stability, while deeper financial and institutional reforms are what’s needed for sustainable growth. Monetary reform can’t be separated from fiscal reform.
In the end, the success of this reform won’t be measured by how sophisticated the software looks. It’ll be measured at the till. The manufacturer will want to know whether imported machinery can be priced without guessing which exchange rate applies tomorrow. The shopkeeper will want to know whether replacement stock costs can be calculated reliably. The farmer will ask whether input prices make sense. The worker will ask whether wages hold their value. The investor will ask whether the rules will still be there when the investment matures. And the ordinary consumer will simply ask whether prices make sense at all. That’s what monetary reform comes down to, in the end: not speeches, not platforms, not policy documents. Prices.
Zimbabwe now has a chance to do something that’s proved difficult for years: build a foreign-exchange market where the price comes from transactions rather than administrative preference. The electronic platform is a useful instrument, but it has to remain just that, an instrument. The real reform is institutional. Zimbabwe has to let the foreign-exchange market communicate scarcity, demand and confidence honestly, even when the message is uncomfortable. That’s the point of markets. They’re not designed to tell governments what they want to hear. They’re mechanisms for discovering information that no single institution possesses on its own.
The RBZ can publish an exchange rate. The market has to believe it. The government can announce a future mono-currency. Businesses and households have to trust it. A law can designate a currency as legal tender. Only economic behaviour can make it credible.
Zimbabwe’s next currency test, then, isn’t whether it can launch another platform. It’s whether it can finally let the market speak. The real test of currency reform isn’t whether the Reserve Bank can produce an exchange rate. It’s whether Zimbabweans can believe it.
Tinotenda Bhunu is an economist by profession. LinkedIn: https://www.linkedin.com/in/tinotenda-bhunu-114645208?utm_source=share&utm_campaign=share_via&utm_content=profile&utm_medium=android_app
Discover more from Etimes
Subscribe to get the latest posts sent to your email.