


By Tinotenda Bhunu
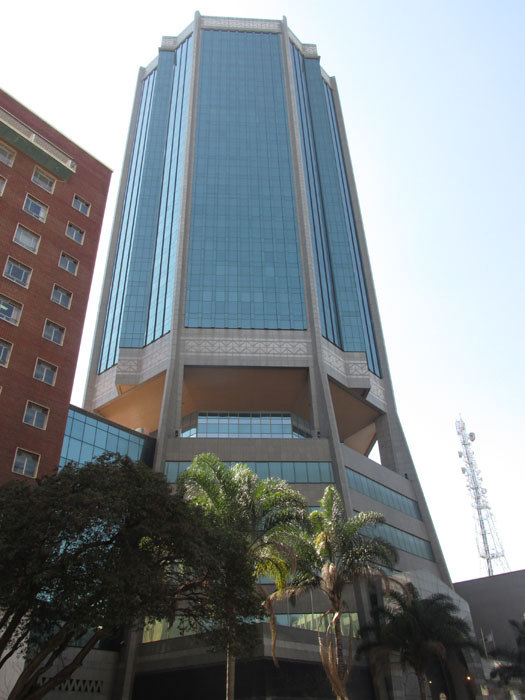
HARARE – THE Reserve Bank of Zimbabwe has cut its Bank Policy Rate from 30% to 27.5%, the second big reduction in a few months. The Targeted Finance Facility rate has dropped too, from 15% to 12.5%, and the all-inclusive lending rate for productive sectors stays capped at 22.5%.
On the surface it’s a textbook move. Inflation is falling, so rates fall with it. But Zimbabwe’s monetary history rarely lets a story stay that simple.

What caught my eye in the latest Monetary Policy Committee statement wasn’t the size of the cut. It was the explanation. The MPC says outright that this isn’t monetary easing. It calls the move a realignment of the policy rate with observed inflation dynamics. That distinction deserves a closer look.
The price of money is finally following the price level
For years, Zimbabwe’s core monetary problem was an unstable currency. When money loses purchasing power fast, contracts get hard to write, saving stops making sense, and entrepreneurs can’t work out what an investment will earn down the line. Interest rates stop being just the price of borrowing. They turn into a way of compensating for monetary uncertainty.
The latest numbers point to a different picture. The MPC puts ZiG inflation at 2.9% in August, edging up to 3.7% in September. It reports US$14.3 billion in foreign-currency inflows over the first eight months of the year, up 37.8% on the same period in 2025. Reserves passed US$2 billion in September, and the exchange rate held in the ZiG25–27 per US$1 range.
These aren’t small things.
Still, this is where Austrian economics offers a useful warning: you can’t manufacture monetary stability by fiddling with the price of credit. Interest rates are signals. They coordinate savers and borrowers and tell entrepreneurs something about the real resources available for investment. Distort that signal long enough and capital flows into projects that only look profitable because money has been made artificially cheap.
That’s why lower rates and easy money are not the same thing.
The RBZ has lowered the rate. Has the market lowered the cost?
Here the announcement leaves monetary theory and lands in the everyday economy. A central bank can declare 27.5%. A bank manager still has to decide whether to lend. A businessman still has to find collateral. A farmer still has to work out whether the harvest can service the loan, and a manufacturer whether anyone will buy the extra output.
So the cut in the TFF rate matters, but it isn’t enough on its own. Credit is only useful when it reaches productive activity and borrowers can reasonably expect to repay. Otherwise, lower administered rates can just become another form of financial repression.
The question shouldn’t be “how low can the rate go?” It should be: what conditions let savings turn into productive investment without wrecking the currency? That’s a far harder question.
Zimbabwe doesn’t need cheap money. It needs credible money.
If there’s one central lesson in the statement, it’s this. Policymakers are tempted to treat interest rates like a volume knob. Turn it down and growth rises, turn it up and inflation falls. Real economies don’t work that mechanically.
Entrepreneurs here need more than cheaper loans. They need confidence that the money they borrow today will hold predictable value, that property works as secure collateral, that contracts get enforced, and that government won’t suddenly rewrite the economics of an investment. Capital is remarkably sensitive to uncertainty. That’s why monetary stability and institutional stability belong in the same conversation. The RBZ can steady the monetary side, but the wider investment climate depends on institutions well beyond the central bank.
The most important sentence may be about savings
Buried under the rate news is something bigger. The MPC says it will keep issuing the ZiG-denominated Term Deposit Facility to build out the domestic yield curve and encourage domestic savings. That matters more than the headline cut suggests.
An economy can’t borrow its way to lasting prosperity. Someone has to save first. Savings are deferred consumption, and they form the pool that investment gets financed from. If Zimbabweans think holding local-currency savings means watching purchasing power drain away, they’ll look elsewhere. That isn’t irrational. It’s a response to incentives.
So the job for monetary authorities isn’t to order people to trust the local currency. It’s to make trusting it the sensible choice. That takes predictable policy, positive real returns where appropriate, and a government that doesn’t undercut the central bank through fiscal indiscipline.
The exchange rate remains the test
The RBZ’s reported exchange-rate stability is an important backdrop, but stability isn’t the goal in itself. What matters is why the currency is stable.
If it rests on stronger exports, remittances, mineral receipts, agricultural output, adequate reserves and credible monetary management, the foundation is solid. If it leans mainly on administrative controls or temporary foreign-currency inflows, that’s a different story. Zimbabwe has seen apparent stability before, only for pressure to come back.
So the takeaway isn’t “the rate is stable, problem solved.” It’s that stability buys a window to build institutions that make future instability less likely.
Growth cannot be printed
The MPC still expects 5% growth in 2026, with mining and agriculture doing much of the work. But this is where monetary policy runs into its limits. The central bank can influence liquidity, interest rates and monetary expectations. It can’t print productivity, create mineral deposits or grow a harvest. It can’t make an entrepreneur spot a profitable opportunity, and it can’t stand in for secure property rights, working markets and predictable rules.
Growth comes from accumulating scarce resources and allocating them better. Money helps that along; it doesn’t replace it. That’s the difference between monetary stimulus and real development.
The danger is celebrating the wrong number
It’s tempting to cheer a drop from 30% to 27.5% as if financing the economy has suddenly become cheap. For the ordinary entrepreneur, what counts is the final lending rate. For the saver, it’s the real return on deposits. For the manufacturer, it’s whether credit can buy machinery that lifts output. For the farmer, it’s whether financing raises production or just covers higher input costs. And for households, it’s whether income keeps its purchasing power.
So this policy can’t be judged by the policy rate alone. The real test is whether Zimbabwe is moving from monetary stabilisation to capital formation.
The RBZ has opened up some policy space. The challenge now is to make sure it isn’t filled by another round of monetary expansion, but by saving, investment and production.
Zimbabwe has already paid dearly to learn that unstable money destroys economic calculation. The next lesson matters just as much: stable money isn’t the destination. It’s the foundation an economy needs to start calculating, saving, investing and producing again.
That, to me, is the real significance of the September MPC decision.
Tinotenda Bhunu is an economist by profession. LinkedIn: https://www.linkedin.com/in/tinotenda-bhunu-114645208?utm_source=share&utm_campaign=share_via&utm_content=profile&utm_medium=android_app
Discover more from Etimes
Subscribe to get the latest posts sent to your email.